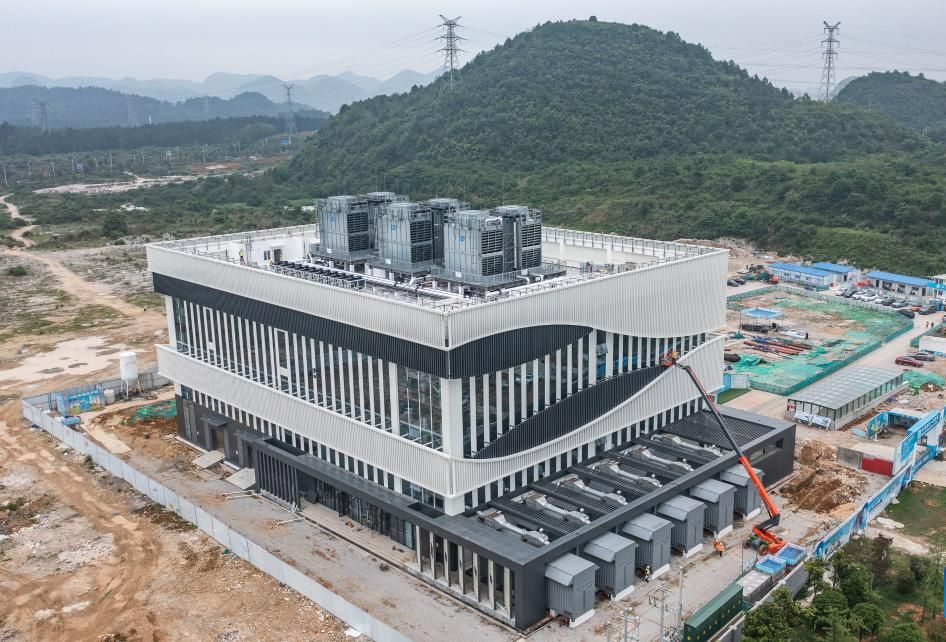
When GlobalFoundries (GF) announced on 14 October that it would provide the technology and operate two new fabs in Malta, New York, the headline was the money. Japan is to provide up to $21bn under a US-Japan trade and investment initiative. The more interesting story for manufacturers is the structure: one country pays, a US-based foundry builds and runs the plants, and Washington takes an equity stake.
A new financing template
The project sits within Japan’s pledge to invest up to $550bn in the US in exchange for changes to tariffs on Japanese imports. That framework also accompanied a cut in US tariffs on Japanese cars from at least 25% to 15%. In a separate agreement, the US Department of Commerce will take an additional stake of around 4% in GF, lifting the government’s holding to roughly 7%. roic (https://www.roic.ai/news/globalfoundries-to-build-two-chip-factories-in-new-york-with-21-billion-japanese-backing-10-14-2026)
The commitments are staged. The first fab, funded by roughly $10bn, is the firm step, while the second “would” be funded and the $21bn is a ceiling. The same analysis notes that the release does not say which Japanese entity provides the money, who owns the fabs, what GF earns as operator, which process nodes will run, or what triggers the second tranche. Those gaps matter to anyone planning supply around this capacity.
Specialty capacity, not leading-edge logic
These fabs are not aimed at cutting-edge AI processors. They target automotive, industrial and connected-infrastructure markets, with support from customers including Renesas, Apple, Cirrus Logic and General Motors. Renesas says it is planning around the plants as an extension of its own production.
That fits GF’s strengths in specialised silicon and advanced packaging, which it says are critical for data centre infrastructure. GF has also agreed to redirect $955 million of its existing CHIPS Act award toward silicon photonics, silicon-germanium and advanced packaging in New York and Vermont. In August it received a further $300m award for silicon photonics. For carmakers and industrial buyers burned by recent shortages, resilience in these mature and specialty segments may matter more than a leading-edge node.
Why brownfield wins
Speed is a quiet advantage. GF says the Malta site is permitted and shovel-ready and can use existing local infrastructure, with groundbreaking expected later this year and the first fab online in 2029. The surrounding Capital Region ecosystem has drawn more than $124bn in semiconductor investment since 2022, according to Empire State Development. Expanding where suppliers, utilities and talent already cluster removes many of the delays that have dogged greenfield projects.
The labour constraint
The jobs numbers need careful reading. GF expects about 27,000 construction and ecosystem jobs but just over 1,000 high-skilled manufacturing roles. Filling even those will not be easy. A workforce analysis involving the Semiconductor Industry Association, McKinsey and the National Science Foundation warns the US could be short up to 157,000 workers by 2030. McKinsey has identified shortages of pipefitters, welders, electricians and carpenters as the greatest challenge to fab construction. One industry summary reports that TSMC cited a lack of experienced US workers to install and commission equipment in its Arizona delays, and flew in Taiwanese specialists. GF says it is working with education and workforce partners, and federal training hubs are being established, but results take years.
The US share of global fab capacity fell from about 37% in 1990 to around 10% in 2022. An SIA and BCG study projected 14% by 2032, against 8% without the CHIPS Act. Two Malta fabs adding roughly 1.8 million 300mm wafers a year is meaningful, but this is steady rebuilding, not a reversal. Demand is growing quickly: Deloitte recorded 22% market growth in 2025, forecasts 26% in 2026, and expects annual sales to reach $2tn by 2036.
Written by:
*Chloe Maluleke
Associate at BRICS+ Consulting Group
Russia & Middle East Specialist
**The Views expressed do not necessarily reflect the views of Independent Media or IOL.
** MORE ARTICLES ON OUR WEBSITE https://bricscg.com/ (https://bricscg.com/)
** Follow @ (https://x.com/brics_daily)brics_daily (https://x.com/brics_daily)on Twitter for daily BRICS+ updates and instagram @brics_daily (https://www.instagram.com/brics_daily?igsh=bmhvbTd0YzA4a2wx)