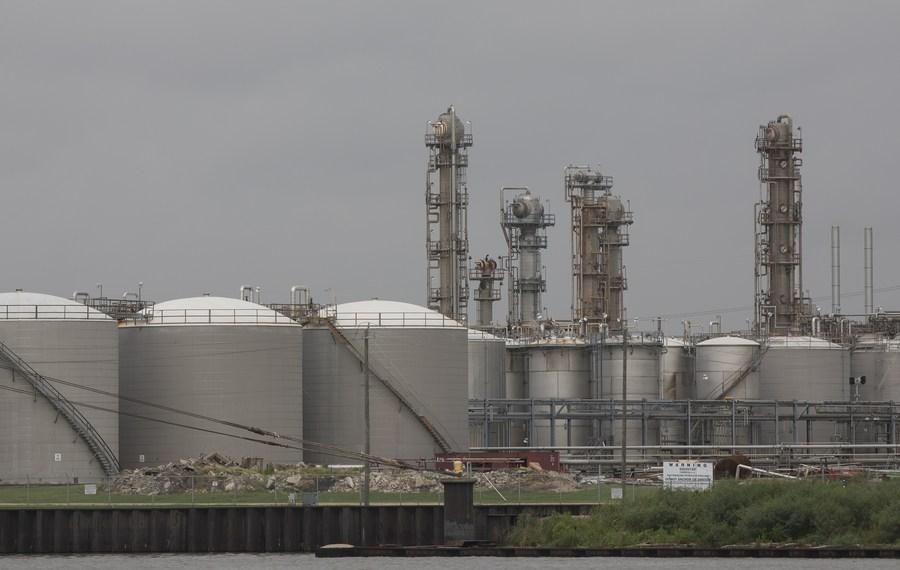
Talk in Washington of a possible ban on American diesel exports is reshaping global oil markets in real time, and the clearest signal is showing up in the spread between US crude futures and the international Brent benchmark. Traders are betting that if US refiners are forced to keep more diesel at home, they will simply process less crude overall, a scenario that has pushed West Texas Intermediate to trade as much as $12 a barrel below Brent, its widest discount since early May.
The catalyst is a fuel-price crisis that has been building for months. US diesel prices touched a record $6.52 a gallon this week, according to AAA figures, prompting President Trump to say at the UN General Assembly that he would favour keeping diesel supplies domestic rather than sending them abroad. Treasury Secretary Scott Bessent went further, confirming that officials were studying whether a full or partial export restriction was workable. The White House then muddied the waters by denying reports of an imminent 90-day ban, while Energy Secretary Chris Wright insisted a blanket ban was not under serious consideration.
That confusion hasn’t stopped the market from pricing in the possibility. Analysts at Wood Mackenzie estimate that a ban could redirect roughly 700,000 barrels a day of surplus diesel and gasoil into domestic storage, filling Gulf Coast inventories within little more than a month and forcing refiners to cut crude throughput by upwards of two million barrels a day, around 12% of current US refining rates. Given that America exports about 1.2 million barrels a day of diesel out of total production of 5.1 million, according to Morgan Stanley, the scale of disruption to refiners’ economics would be substantial.
The consequences are already rippling well beyond US shores. Europe’s diesel premium over Brent crude, the closely watched crack spread, jumped above $95 a barrel this week, a record in data stretching back to 2011, as the region’s top external supplier signalled it might restrict flows. Citi analysts warned that any US restriction could squeeze global supply further while handing an advantage to Asian refiners left to pick up the slack.
Refining shares have felt the strain too. Valero, Marathon Petroleum and Phillips 66 all sold off through the week even as their underlying margins remain historically strong, Valero’s Gulf Coast diesel margin, for instance, has roughly tripled year-on-year. Energy economist Philip Verleger cautioned that a ban risks doing lasting damage to America’s position as a fuel exporter, likening the potential fallout to President Nixon’s 1973 soybean embargo, after which buyers permanently redirected their purchases elsewhere.
Complicating matters further is a separate squeeze on shipping. The war involving Iran has driven freight rates sharply higher and tightened vessel availability, denting the usual arbitrage logic that a widening WTI–Brent spread should encourage more US exports. Freight analysts at Signal Maritime note that hauling crude from the US Gulf Coast to Asia now costs around $50 million per voyage on a very large crude carrier, roughly three times pre-war levels. Even with WTI trading at a persistent discount of $4 or more to Brent since early July, US crude exports have barely budged, edging up just 45,000 barrels a day between July and August, and are on track to fall for a third straight month in September.
As one trader put it, a wide paper spread is an invitation to test the arbitrage rather than proof that it is genuinely open. With the November midterm elections adding political urgency to already-record pump prices, and with no formal policy yet signed, the coming weeks look set to test how much further the crude and diesel markets can diverge before something has to give, either at the pump, in refiners’ margins, or in Washington’s policy calculus.
Written by:
*Chloe Maluleke
Associate at BRICS+ Consulting Group
Russia & Middle East Specialist
**The Views expressed do not necessarily reflect the views of Independent Media or IOL.
** MORE ARTICLES ON OUR WEBSITE https://bricscg.com/ (https://bricscg.com/)
** Follow @ (https://x.com/brics_daily)brics_daily (https://x.com/brics_daily)on Twitter for daily BRICS+ updates and instagram @brics_daily (https://www.instagram.com/brics_daily?igsh=bmhvbTd0YzA4a2wx)