Where the Growth Actually Came From
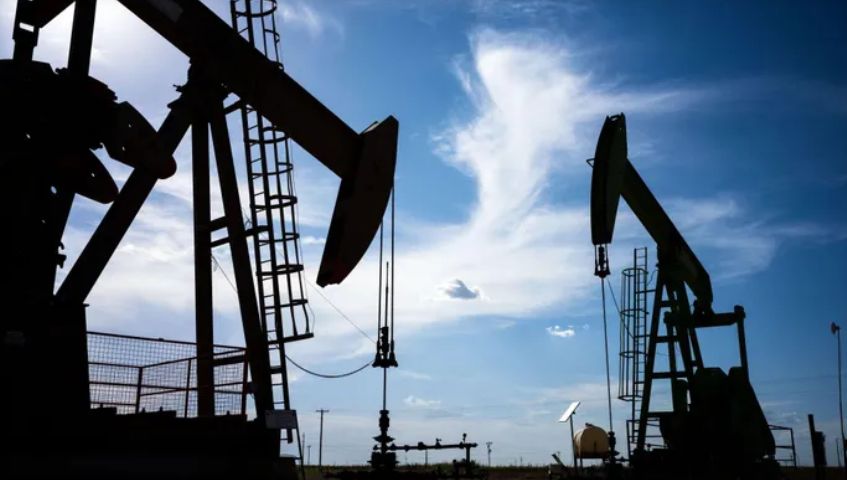
Oil and gas revenue rose 41.7 percent to Shs326.27 billion, the fastest-growing component by far, while mining revenue climbed to Shs336.97 billion. Direct government revenue from the sector increased from Shs481.27 billion to Shs606.36 billion, though that still represents only about 2.18 percent of total government revenue, a reminder of how much runway exists before extractives become a dominant fiscal pillar. State Minister for Planning Amos Lugoloobi framed the numbers as proof of the sector’s unrealised potential if properly managed, a careful way of saying Uganda knows it has not yet captured anywhere close to what this resource base could eventually deliver.
The Oil Era Is Genuinely Close This Time
Skepticism about Uganda’s oil timeline is earned. The country discovered commercial reserves in the Albertine Graben back in 2006, and the production date has slipped from 2018 to 2024 to 2025 and now to 2026. But the operational indicators this time look different from previous false starts. TotalEnergies’ Tilenga project has drilled 198 wells against a target of 170, and CNOOC’s Kingfisher project has completed all 21 wells needed for initial output, according to the Petroleum Authority of Uganda. Recoverable reserves have been revised upward to 1.65 billion barrels, and the government is targeting first crude exports via the East African Crude Oil Pipeline around October 2026, with peak national output projected between 230,000 and 260,000 barrels a day.
The Refinery Question Is the One to Watch
This is where Uganda’s strategy diverges from the typical African oil story, and where the real risk sits. Rather than exporting raw crude indefinitely, as Nigeria did for decades while importing refined fuel back at a markup, Uganda signed a deal with UAE-based Alpha MBM Investments in 2025 for a 60,000-barrel-per-day refinery in Hoima, with the Uganda National Oil Company holding 40 percent. The logic mirrors what Senegal has tried with its Sangomar project and what Ghana attempted, with mixed success, around Jubilee, keeping a meaningful state stake so the resource rent doesn’t flow entirely offshore. But UNOC itself has now pointed to a 2030 launch date for the refinery, meaning Uganda could be exporting unrefined crude for several years before any domestic value addition materialises. That gap is exactly where Nigeria lost decades of potential industrial benefit, continuing to ship crude abroad while its own refineries sat idle or unbuilt.
Revenue Before Production Is a Double-Edged Sign
Uganda has already banked over 1.4 billion dollars in tax and non-tax revenue before producing any oil, and projections suggest 1 to 2.5 billion dollars annually once production stabilises, feeding into the government’s Ten-Fold Growth Strategy aimed at a 500 billion dollar GDP by 2040. That is an encouraging fiscal head start compared to countries that waited for production to begin generating meaningful state income. But Bank of Uganda governor Michael Atingi-Ego has already warned that resource extraction alone will not guarantee prosperity, a caution grounded in enough African precedent to take seriously. The revenue growth in this EITI report is real and worth noting. Whether Uganda converts it into lasting industrial capacity, rather than another chapter in the continent’s long history of exporting wealth before it can refine it, will depend entirely on what happens between first oil and that 2030 refinery target.
Written by:
*Dr Iqbal Survé
Past chairman of the BRICS Business Council and co-chairman of the BRICS Media Forum and the BRNN
*Sesona Mdlokovana
Associate at BRICS+ Consulting Group
Africa Specialist
**The Views expressed do not necessarily reflect the views of Independent Media or IOL.
** MORE ARTICLES ON OUR WEBSITE https://bricscg.com/ (https://bricscg.com/)
** Follow @ (https://x.com/brics_daily)brics_daily (https://x.com/brics_daily)on Twitter for daily BRICS+ updates and instagram @brics_daily (https://www.instagram.com/brics_daily?igsh=bmhvbTd0YzA4a2wx)